Buy futureskills.eu ?
We are moving the project
futureskills.eu .
Are you interested in purchasing the domain
futureskills.eu ?
domain@kv-gmbh.de · 0541-91531010
Buy futureskills.eu ?
What is a primary mortgage financing?
A primary mortgage financing refers to the initial loan that a borrower obtains from a lender to purchase a home or property. This type of financing is typically used to cover the majority of the purchase price of the property, and is secured by the property itself. The borrower makes regular payments to the lender over a set period of time, usually 15 or 30 years, until the loan is fully repaid. Primary mortgage financing is a common way for individuals to become homeowners without having to pay the full purchase price upfront. **
How does the mortgage work in Monopoly?
In Monopoly, players can purchase properties when they land on them. If a player lands on an unowned property and chooses not to buy it, the property goes up for auction. If a player cannot afford to purchase a property, they have the option to mortgage their own properties to raise funds. When a property is mortgaged, the owner receives cash equal to half of the property's value, but they must pay 10% interest when they unmortgage the property. **

Similar search terms for Mortgage
Top-Angebote
Products related to Mortgage:
-
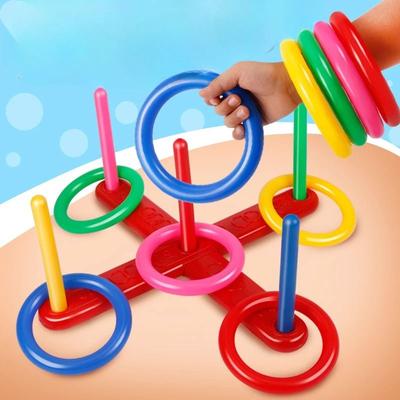
Uplifted Finds Interactive Ring Toss Training System Professional Early Education & Pediatric Fitness Infrastructure Interactive Ring Toss Training System Professional Early Education & Pediatric Fitness InfrastructureCommand ultimate developmental confidence with the Interactive Ring Toss Training System, a highperformance educational solution specifically engineered to act as a comprehensive tool for elite organization and superior technical ergonomics. Built...52,97 $*Shipping: 0,00 $Secure redirect to the provider
-
Logitech Crayon for Education USB-C Digital Pencil for iPad - Classic Blue (914-000080)This Bluetooth-enabled stylus is compatible with a wide range of iPad models including iPad Pro, iPad Air, and iPad mini. Key features include tilt sensitivity, palm rejection technology, rechargeable battery, and 1.2-meter drop protection. The device weighs just 20 grams and comes with a 3-year warranty.101,99 £*Shipping: 0,00 £Secure redirect to the provider
-
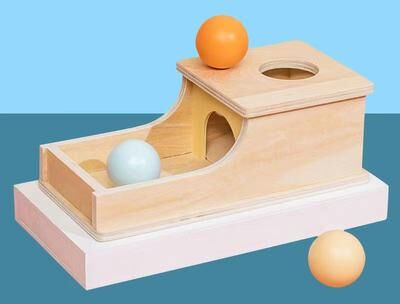
Tiny Tots Teens Trends Drawer Game Early Education Montessori Wooden Pitch Ball Box Preschool Learning Training Toy Drawer Game Early Education Montessori Wooden Pitch Ball Box Preschool Learning Training ToyThis Montessori Wooden Pitch Ball Box Drawer Game is a thoughtfully designed earlyeducation toy that transforms playtime into purposeful learning. Crafted for toddlers and preschoolers, it offers a handson, engaging way to support key developmental...39,97 $*Shipping: 0,00 $Secure redirect to the provider
-
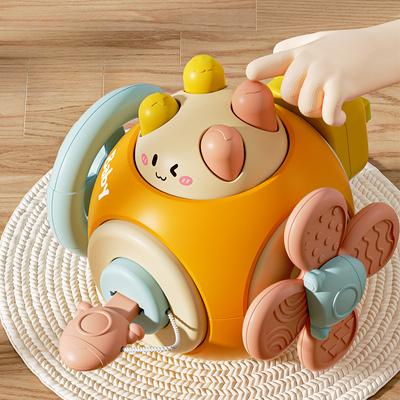
Tiny Tots Teens Trends Montessori Baby Training, Infant Puzzle Early Education Toys, Busy Hand Grasping Ball For Baby Montessori Baby Training, Infant Puzzle Early Education Toys, Busy Hand Grasping Ball For BabyIntroduce Your Baby to the World of Learning The Infant Puzzle Early Education Toys are designed to foster cognitive and physical development in your little one. This Multifunctional Busy Ball for Montessori Baby Training is ideal for enhancing...79,97 $*Shipping: 0,00 $Secure redirect to the provider

-
Where can I get a mortgage deed?
You can obtain a mortgage deed from a mortgage lender or financial institution that is providing you with the loan for purchasing a property. The mortgage deed is a legal document that outlines the terms and conditions of the mortgage agreement between the borrower and the lender. It is typically prepared by the lender's legal team and signed by both parties before the loan is disbursed. **
-
Can the mortgage on the house increase?
Yes, the mortgage on a house can increase under certain circumstances. For example, if the homeowner has an adjustable-rate mortgage, the interest rate can increase over time, causing the monthly mortgage payment to go up. Additionally, if the homeowner has a mortgage with an escrow account for property taxes and homeowners insurance, an increase in these expenses can also lead to an increase in the monthly mortgage payment. Finally, if the homeowner takes out a home equity loan or line of credit, this can also increase the overall debt secured by the house. **
-
What do I need to cancel a mortgage?
To cancel a mortgage, you typically need to pay off the remaining balance of the loan. This can be done by making a lump sum payment for the full amount owed. Once the loan is paid off, the lender will provide you with a satisfaction of mortgage document, which officially cancels the mortgage lien on the property. It's important to follow the specific procedures outlined by your lender to ensure the mortgage is properly canceled. **
-
How can I tell if a mortgage still exists?
To determine if a mortgage still exists on a property, you can start by checking the public records at the county recorder's office where the property is located. Look for the deed of trust or mortgage document that was originally recorded when the loan was taken out. You can also contact the lender directly to inquire about the status of the mortgage and any outstanding balance. Additionally, you can request a copy of your credit report, which should list any current mortgages or liens on your property. **
How was the house purchased without a mortgage deed?
The house was purchased without a mortgage deed through a cash transaction. This means that the buyer paid for the house in full with their own funds, rather than taking out a mortgage loan from a bank or other financial institution. This type of transaction is common in situations where the buyer has enough savings or access to funds to purchase the property outright, without the need for a mortgage. **
Should the mortgage be cancelled or transferred to another bank?
Whether the mortgage should be cancelled or transferred to another bank depends on various factors such as the terms of the current mortgage, the interest rates offered by other banks, and any penalties for cancelling the mortgage early. It is important to carefully evaluate these factors and consider the potential costs and benefits before making a decision. Consulting with a financial advisor or mortgage specialist can also help in making an informed decision. **
Top-Angebote
Products related to Mortgage:
-
Perfect Picks Market Geometric Building Blocks Set For Kids Early Education Intelligence Development Toy Geometric Building Blocks Set For Kids Early Education Intelligence Development ToyUnlock your child's potential with this early education equipment designed to stimulate creativity and intelligence! This geometric set is the perfect building block toy for boys, helping to develop problemsolving skills while having fun. The...35,97 $*Shipping: 0,00 $Secure redirect to the provider
-
Uplifted Finds Interactive Ring Toss Training System Professional Early Education & Pediatric Fitness Infrastructure Interactive Ring Toss Training System Professional Early Education & Pediatric Fitness InfrastructureCommand ultimate developmental confidence with the Interactive Ring Toss Training System, a highperformance educational solution specifically engineered to act as a comprehensive tool for elite organization and superior technical ergonomics. Built...52,97 $*Shipping: 0,00 $Secure redirect to the provider
-
Logitech Crayon for Education USB-C Digital Pencil for iPad - Classic Blue (914-000080)This Bluetooth-enabled stylus is compatible with a wide range of iPad models including iPad Pro, iPad Air, and iPad mini. Key features include tilt sensitivity, palm rejection technology, rechargeable battery, and 1.2-meter drop protection. The device weighs just 20 grams and comes with a 3-year warranty.101,99 £*Shipping: 0,00 £Secure redirect to the provider
-
What is a primary mortgage financing?
A primary mortgage financing refers to the initial loan that a borrower obtains from a lender to purchase a home or property. This type of financing is typically used to cover the majority of the purchase price of the property, and is secured by the property itself. The borrower makes regular payments to the lender over a set period of time, usually 15 or 30 years, until the loan is fully repaid. Primary mortgage financing is a common way for individuals to become homeowners without having to pay the full purchase price upfront. **
-
How does the mortgage work in Monopoly?
In Monopoly, players can purchase properties when they land on them. If a player lands on an unowned property and chooses not to buy it, the property goes up for auction. If a player cannot afford to purchase a property, they have the option to mortgage their own properties to raise funds. When a property is mortgaged, the owner receives cash equal to half of the property's value, but they must pay 10% interest when they unmortgage the property. **
-
Where can I get a mortgage deed?
You can obtain a mortgage deed from a mortgage lender or financial institution that is providing you with the loan for purchasing a property. The mortgage deed is a legal document that outlines the terms and conditions of the mortgage agreement between the borrower and the lender. It is typically prepared by the lender's legal team and signed by both parties before the loan is disbursed. **
-
Can the mortgage on the house increase?
Yes, the mortgage on a house can increase under certain circumstances. For example, if the homeowner has an adjustable-rate mortgage, the interest rate can increase over time, causing the monthly mortgage payment to go up. Additionally, if the homeowner has a mortgage with an escrow account for property taxes and homeowners insurance, an increase in these expenses can also lead to an increase in the monthly mortgage payment. Finally, if the homeowner takes out a home equity loan or line of credit, this can also increase the overall debt secured by the house. **
Similar search terms for Mortgage
-
Tiny Tots Teens Trends Drawer Game Early Education Montessori Wooden Pitch Ball Box Preschool Learning Training Toy Drawer Game Early Education Montessori Wooden Pitch Ball Box Preschool Learning Training ToyThis Montessori Wooden Pitch Ball Box Drawer Game is a thoughtfully designed earlyeducation toy that transforms playtime into purposeful learning. Crafted for toddlers and preschoolers, it offers a handson, engaging way to support key developmental...39,97 $*Shipping: 0,00 $Secure redirect to the provider
-
Tiny Tots Teens Trends Montessori Baby Training, Infant Puzzle Early Education Toys, Busy Hand Grasping Ball For Baby Montessori Baby Training, Infant Puzzle Early Education Toys, Busy Hand Grasping Ball For BabyIntroduce Your Baby to the World of Learning The Infant Puzzle Early Education Toys are designed to foster cognitive and physical development in your little one. This Multifunctional Busy Ball for Montessori Baby Training is ideal for enhancing...79,97 $*Shipping: 0,00 $Secure redirect to the provider
-
What do I need to cancel a mortgage?
To cancel a mortgage, you typically need to pay off the remaining balance of the loan. This can be done by making a lump sum payment for the full amount owed. Once the loan is paid off, the lender will provide you with a satisfaction of mortgage document, which officially cancels the mortgage lien on the property. It's important to follow the specific procedures outlined by your lender to ensure the mortgage is properly canceled. **
-
How can I tell if a mortgage still exists?
To determine if a mortgage still exists on a property, you can start by checking the public records at the county recorder's office where the property is located. Look for the deed of trust or mortgage document that was originally recorded when the loan was taken out. You can also contact the lender directly to inquire about the status of the mortgage and any outstanding balance. Additionally, you can request a copy of your credit report, which should list any current mortgages or liens on your property. **
-
How was the house purchased without a mortgage deed?
The house was purchased without a mortgage deed through a cash transaction. This means that the buyer paid for the house in full with their own funds, rather than taking out a mortgage loan from a bank or other financial institution. This type of transaction is common in situations where the buyer has enough savings or access to funds to purchase the property outright, without the need for a mortgage. **
-
Should the mortgage be cancelled or transferred to another bank?
Whether the mortgage should be cancelled or transferred to another bank depends on various factors such as the terms of the current mortgage, the interest rates offered by other banks, and any penalties for cancelling the mortgage early. It is important to carefully evaluate these factors and consider the potential costs and benefits before making a decision. Consulting with a financial advisor or mortgage specialist can also help in making an informed decision. **
* All prices are inclusive of VAT and, if applicable, plus shipping costs. The offer information is based on the details provided by the respective shop and is updated through automated processes. Real-time updates do not occur, so deviations can occur in individual cases. ** Note: Parts of this content were created by AI.